Ron-Osborne-Two Awards_Image Provided by Sperry CGA 800x315

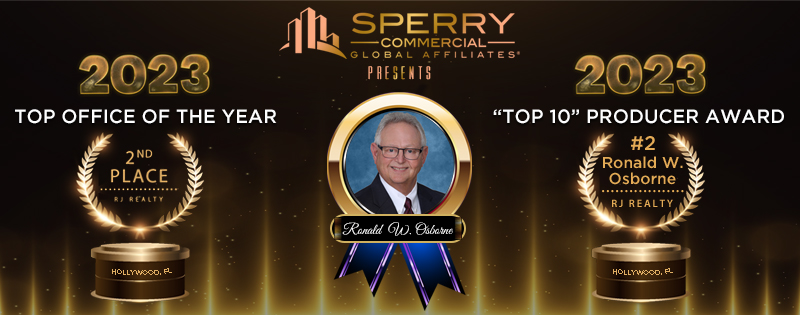
Ron Osborne, Managing Director/Broker of SperryCGA | RJ Realty, has been recognized as a Top Producer at Sperry Commercial Global Affiliates for the third consecutive year.

Each year, the firm bestows this esteemed accolade upon the top 10 brokers who achieve the highest grossing volume.

“Over each of these years, I have consistently elevated my production levels, culminating in being honored as the 2nd highest producer in 2023,” commented Osborne. “This remarkable accomplishment is largely a result of the unwavering trust my clients have placed in my abilities, along with the invaluable support from my colleagues, family, friends, mentors, and influential figures in the business community. As I settle in to 2024, I am confident that with that continued support, I will be reach my ongoing aspiration of attaining the coveted position of Top Producer.”

The firm, RJ Realty, was also recognized as a Top Producing Office in the Sperry network of 60+ offices.  Mr. Osborne the Managing Director/Broker, attributes the honor to the hard work of his team.

The team is laser focused on clients’ needs and helping them achieve their goals. Most of RJ Realty’s clients have worked with Mr. Osborne for years and consider him and his team part of their advisory team.  The RJ Realty team always puts the client’s needs first, from assisting them in financing a new acquisition, to helping them determine the right time to exit a property.  Ron always advises his clients not to just buy for a return on the investment, but to also place location as just as important – sometimes even more than the current cap rate.


house with calendar_shutterstock_1806105649 800x315

The Mortgage Bankers Association has revised upward its estimate of debt maturing in 2024.

Because of the number of extensions and modifications that lenders have been granting borrowers in the past few years, the amount of CRE mortgages maturing this year is expected to increase from $659 billion to $929 billion.

“The lack of transactions and other activity last year, coupled with built-in extension options and lender and servicer flexibility, has meant that many loans that were set to mature in 2023 have been extended or otherwise modified and will now mature in 2024, 2026, 2028 or in other coming years,” said Jamie Woodwell, head of commercial real estate research at MBA.

This new estimate expands the universe of potential distress that could enter the market. At the same time, though, the increase in maturities this year could also have the unexpected consequence of generating more price transparency in the market. The uncertainty surrounding interest rates and questions about property values and fundamentals have led to fewer sales and financing transactions. However, the mortgages due to mature in 2024 and clarifications in other areas should help break up congestions in the markets.

The CRE loans maturing this year vary both by investor type and property type. For instance, just $28 billion, or 3 percent, of the outstanding balance of multifamily and healthcare mortgages either held or guaranteed by Fannie Mae, Freddie Mac, FHA, and Ginnie Mae will mature in 2024. In addition, life insurance companies will see $59 billion, 8 percent, of their outstanding mortgage balances mature in 2024. However, $441 billion, or 25 percent, of the outstanding balance of mortgages held by depositories; $234 billion, 31 percent, in CMBS, CLOs, or other ABS; and $168 billion, 36 percent, of the mortgages held by credit companies, in warehouse, or by other lenders, will mature this year.

In terms of property type, 12 percent of mortgages backed by multifamily properties will mature in 2024. Also, 17 percent of mortgages backed by retail and 18 percent backed by healthcare properties will mature this year. In addition, 25 percent of loans backed by office properties will come due in 2024. Finally, 27 percent of industrial loans and 38 percent of hotel/motel loans will mature this year, as well.


Source:  GlobeSt.


rising expenses_money with upward trending graph_canstockphoto6222096 800x315

By Jay Steinman and Karina Leiter
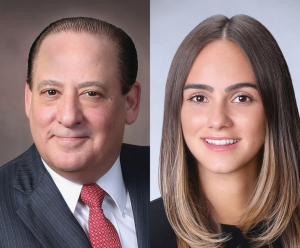
Jay Steinman, left, and Karina Leiter, right, of Duane Morris. Courtesy photos.

Jay Steinman, left, and Karina Leiter, right, of Duane Morris. Courtesy photos.

Loan defaults and workouts are on the rise again due to a confluence of factors causing headwinds including: the surge in interest rates and real estate owners inability to refinance maturing loans at affordable rates; the continued rise in the cost of certain materials needed for renovation and construction; the staggering cost of flood and windstorm coverage and the impossibility of even obtaining coverage; and the loan maturing in the near future without satisfactory options to refinance or be otherwise paid off on time.

Anticipating the fallout from potentially billions of dollars in distressed loans, lenders must be on high alert. Drawing from lessons learned in the last two historical downturns, where we witnessed unprepared lenders face severe consequences, it is imperative for lenders and financial institutions to act now.

Identifying distressed borrowers and projects is a critical first step, acknowledging the inevitability that many loans are already or may default in the near future. By taking proactive measures now, lenders can not only brace for the storm but also enhance and protect their available legal remedies in the event of a borrower’s default.

The subsequent steps outlined in this article offer a strategic guide for lenders, empowering them to navigate the complexities of loan workouts and enforcement actions with resilience and foresight.

Nonwaiver Letter

If a default has occurred the lender may want to have counsel draft a form of reservation of rights or nonwaiver letter. The letter should identify the known breaches and should also include “nonwaiver” type language which generally states that notwithstanding the breach or default the lender is reserving all rights under the loan documents and is not waiving any right or remedy thereafter even though it may be taking no action at that time to enforce its remedies.

Review Loan Documents

Before discussing a potential loan workout with a borrower or proceeding to exercise the remedies available, lenders should first evaluate their legal position, which includes conducting a thorough review of all loan documents including all organizational documents, title insurance policies, surveys and other due diligence materials received at closing and thereafter. Taking inventory of all collateral is also important if possible. A careful review of the loan file should be conducted to identify any documents and correspondence that may adversely impact enforcement of remedies. You don’t want to go to war with defective loan documents or due diligence issues that should have been addressed before the loan closed or thereafter.

We recommend that a new pair of eyes go through all relevant documents. Unfortunately, it is human nature that the counsel who handled the loan previously may have missed or overlooked something that will become critical during the workout, foreclosure or REO sale thereafter. Further, lenders should consider whether there are any technical issues with the loan documents and loan structure that could complicate enforcement.

Lenders should pay particular attention to what constitutes an “event of default” under the loan documents, keeping in mind the borrower’s financial and non-financial covenants, as well as the remedies available to both parties when an event of default occurs, including, without limitation, any required notices and applicable cure periods.

Perform Updated Diligence

After the lender and its counsel have reviewed the loan documents and defects if any have been identified, it is also prudent to conduct an updated review of diligence items with respect to the collateral which secures its loan, the borrower and any guarantors, including, without limitation, updated searches, title, review of financial information with respect to the property, borrower and any guarantor and current organizational documents. The lender may also want to obtain an updated appraisal and environmental audit.

By performing loan document review and analysis and the updated diligence, the lender will better understand its position and leverage before entering into negotiations with the borrower. Any existing liens or other title defects may complicate any foreclosure sale and further slowdown enforcement, which is already a lengthy process.

Execute a Pre-Negotiation Letter

Before beginning any substantive discussions with a borrower regarding a loan modification or forbearance agreement, we recommend that the lender require that the borrow and any guarantor execute a pre-negotiation letter agreement. A pre-negotiation letter agreement sets forth the parameters of the negotiations between borrower and lender prior to memorializing such negotiations in any written document. We recommend that the pre-negotiation letter agreement include a requirement that the borrower and any guarantors provide certain updated due diligence information described above to the extent that the lender’s file does not include this information.

Workout Negotiations

To the extent that a lender elects to withhold from enforcing its rights under the loan documents as a result of a borrower or lender default, the parties should enter into a loan modification or forbearance agreement. Generally speaking, it is best practice that the forbearance agreement include an acknowledgement by the borrower and any guarantors that a default has occurred under the loan documents and that the lender agrees to refrain from exercising its rights and remedies for a specific period of time, provided that the borrower and any guarantor comply with the conditions set out in the loan modification or forbearance agreement. The forbearance agreement at a minimum should include the following provisions: recitals, admission of outstanding loan balance, debt service payments during the period of forbearance, forbearance period, conditions precedent to the effectiveness of the forbearance agreement, forbearance events of default and remedies, retroactive default interest from the date of the initial default, release of lender, waiver of bankruptcy stay, consent to appointment of a receiver and foreclosure, agreement not to contest foreclosure and reaffirmation of guaranty.

Enforcement Actions

The process for enforcing a loan through foreclosure varies across jurisdictions, so lenders should understand the unique process in their jurisdiction.

The loan documents may allow the lender to ask a court to appoint a receiver to take possession of and manage the property until the foreclosure is finalized and the property is sold through a foreclosure sale; provided, however, the applicable standard for the appointment of a receiver varies by jurisdiction. Lenders should also be aware that language in a loan document that allows a lender to “request” or “apply” for the appointment of a receiver does not necessarily entitle the lender to that appointment in most cases. Most states have recently adopted a model receivership law making it a bit easier to obtain a receiver in different venues around the country.

In light of the current interest rate environment, borrowers are getting more desperate to hold onto their current financing and will employ various delay tactics to prevent lenders from enforcing their rights. These types of defensive tactics can significantly increase the time and expense associated with enforcement of the loan.

Be Aware of Lender Liability

Throughout the workout and/or enforcement process, lenders should be aware of their exposure to potential lender liability claims. Borrowers may bring claims based on a lenders’ failure to honor its obligations under the loan documents, unreasonably delay, or lack of good faith. These claims will open lenders up to discovery, which can be time-consuming and expensive. Therefore, lenders should keep in mind that all non-privileged communications may be discoverable and keep all internal and external communication professional. Lenders should ensure that all discussions with the borrower and any guarantor are well documented and subject to confidentiality requirements set forth in the pre-negotiation letter agreement and/or forbearance agreement.

In conclusion, with loan defaults and workouts on the rise due to various challenges, lenders must act proactively to safeguard their interests. By taking measures now, lenders can enhance their readiness to navigate the challenges ahead, protecting both their assets and legal remedies. In the evolving financial landscape, foresight and preparedness are key to resilience.

—Meagen E. Leary and Phillip Hudson, attorneys with the firm, assisted in the preparation of this article.


Source: DBR
cash held tightly in a vice with a white background_canstockphoto20020 800x315

The Federal Reserve’s Senior Loan Officer Opinion Survey on Bank Lending Practices (SLOOS) regularly checks with banks to better understand their lending landscape. The short take for commercial real estate from the most recent survey is that even tighter underwriting standards can be expected in the future.

And while easing interest rates are eventually expected to support relatively low demand from borrowers, that is unlikely to happen until May or June.

“Over the fourth quarter, significant net shares of banks reported tightening standards for all types of CRE loans,” the report noted. “Such tightening was more widely reported by other banks [or those with less than $50 billion in assets] than by large banks.” Tightening standards particularly by the “other banks” category were also true for multifamily loans.


“Major net shares of banks reported weaker demand for loans secured by nonfarm nonresidential and multifamily residential properties, and a significant net share of banks reported weaker demand for construction and land development loans,” they added. “Similarly, significant net shares of foreign banks reported tighter standards and weaker demand for CRE loans over the fourth quarter.”

The net percent of respondents that are tightening standards for CRE loans is a little shy of the 2020 pandemic peak and still near the 2009 apex of the Global Financial Crisis. Also, the net percent of domestic respondents reporting stronger demand for CRE loans is even worse than the depths after the GFC.

Dave Sloan, a senior economist at Continuum Economics, told Reuters that the results are “unlikely to generate any urgency for easing.” Banks expect demand for loans to increase as interest rates fall, but with signaling from the Fed, this is unlikely to happen until May or June at the earliest.

“The most frequently cited reasons for expecting to tighten lending standards over 2024, reported by major net shares of banks, included an expected deterioration in collateral values, a less favorable economic outlook, an expected deterioration in credit quality of the bank’s loan portfolio, an expected reduction in risk tolerance, an expected deterioration in the bank’s liquidity position, and increased concerns about funding costs and about the effects of legislative or regulatory changes,” explained the Fed.

More colloquially, at issue is fear on the part of banks, still around since the closuresof Signature Bank, Silicon Valley Bank, and First Republic Bank in the early part of 2023. Roughly a week after shares of New York City Bancorp — which bought most of the assets of Signature, including its CRE loan portfolio — started plummeting, they’re still in freefall. Shares went from about $10.30 or so to $4.20 at the close of Feb. 6, a drop of almost 60%.

The problems facing New York Community were more than Signature. A New York co-op loan that wasn’t in default nevertheless is now up from sale because of “a unique feature that pre-funded capital expenditures.” There was also an “additional charge-off on an office loan that went non-accrual during the third quarter, based on an updated valuation.” But they were all related to commercial real estate. And what rattles one bank rattles many more.


Source:  GlobeSt.


future green road sign with dramatic clouds and sky_canstockphoto3157426 800x315
The first proper U.S. financial market tremors of 2024 have been felt and unsurprisingly, perhaps, commercial real estate is at the heart of the dislocation.
Unsurprising, at least, to the thousands who descended on Miami this week for the investor conferences and meetings collectively termed “Hedge Fund Week,” who put commercial real estate as perhaps the most scarlet of red flags for the year ahead.
Just as New York Community Bancorp shares were plunging nearly 40%, unleashing the biggest sell-off in regional U.S. bank stocks since the shock of March last year, some of the most powerful names in finance were sounding the warning.
“There’s going to be a reckoning. How contained that is is TBD (to be decided),” Drew McKnight, co-CEO at Fortress Investment Group, said on a panel at the iConnections Global Alts 2024 conference on Tuesday.
“Even in a benign environment, even in a soft landing … that is an area that will provide stress. I don’t think it will be a bloodbath … but there is turmoil, and the worst of that turmoil is yet to come,” he said.
McKnight was one of four on the “Wall Street Titans Panel” alongside Third Point’s Dan Loeb, Oaktree Capital Management’s Armen Panossian and Apollo’s John Zito. Hundreds of billions of dollars of assets under collective management, and a collective wariness towards commercial real estate (CRE).
To be sure, none called an immediate crisis or crash. And the Federal Reserve’s rapid and highly effective response to the regional banking shock last March shows that policymakers have the hoses to put out fires were they to appear again.
Instead, there could be a steady drip over the coming years of borrowers refinancing mortgages at significantly higher interest rates, buildings remaining empty, and asset values heading south.
“It’s not going to happen overnight, but I can see lots of situations where the debt comes due that it’s going to be very hard to warrant anywhere close to where these valuations are today,” warned Apollo’s Zito.

MATURITY WALL OF WORRY

According to Goldman Sachs, some $1.2 trillion of commercial mortgages are scheduled to mature this year and next. That’s almost a quarter of all outstanding commercial mortgages, and the highest recorded level going back to 2008. The biggest single holder are banks with a 40% share.
Other estimates put the “maturity wall” as high as $1.5 trillion.
Whatever the number, it is lot of borrowers having to refinance mortgages at two or even three times higher rates thanks to the 500 basis points of Fed rate hikes over 2022-23.
They won’t all be able to do that, putting lenders on the hook too. And small U.S. banks are on the hook more than most – Apollo’s chief economist Torsten Slok estimates almost 70% of all CRE loans outstanding is held by small banks.
Barry Sternlicht, CEO of Starwood Capital Group, an investment firm focusing on real estate with around $115 billion of assets under management, sounded an even gloomier note on the CRE sector and banks that lend to it.
“The office market has an existential crisis right now,” Sternlicht told the Global Alts conference. “It’s a $3 trillion asset class that is probably worth $1.8 trillion. There’s $1.2 trillion of losses spread somewhere, and nobody knows exactly where it all is.”
Yet all that said, the Fed’s response to last year’s regional banking shock – namely the liquidity injection via the Bank Term Funding Program (BTFP) – and the subsequent rebound across financial markets are powerful reminders not to get too carried away.
The Fed has said the BTFP will be wound down in March, but few investors would bet against the central bank quickly reopening it or even creating new tools to provide liquidity or backstop the market should the need arise.


Source:  Reuters

precarious situation_hanging on by a thread_shutterstock_1646953684 800x315

“Bad” doesn’t adequately express the last few days for New York Community Bancorp.

As the close of Thursday, shares were down 44.6% after the bank revealed a 2023 Q4 loss of $252 million rather than the Q3 $207 million gain. Markets remembered that there are still significant concerns about commercial real estate and its loans.

New York Community had acquired much of the deposits and loan assets from failed Signature Bank, and it added a $552 million provision for future credit losses, plus $185 million in net charge-offs, plus cut dividends by 70% to bolster capital.

Despite repeated assurances from the Federal Reserve and the Treasury department that banks are fundamentally sound, real-time results for banks have become reminders to markets that all is apparently not well.

The problems facing New York Community were more than Signature. A New York co-op loan that wasn’t in default nevertheless is now up from sale because of “a unique feature that pre-funded capital expenditures.” There was also an “additional charge-off on an office loan that went non-accrual during the third quarter, based on an updated valuation.”

Even worse, all this was unanticipated by investors because the bank had not prepared markets for the bad news.

From a market view, compounding all this was that the acquisitions from Signature and 2022’s acquisition of Flagstar Bancorp boosted New York Community’s total assets to more than $100 billion. That put the institution, as it noted, “firmly in the Category IV large bank class of banks between $100 billion and $250 billion in assets and subjecting us to enhanced prudential standards, including risk-based and leverage capital requirements, liquidity standards, requirements for overall risk management and stress testing.”

Moody’s placed the bank on review for a downgrade

But there was compounding news from elsewhere in the world, as the Wall Street Journal reminded. Azora Bank of Japan saw shares drop 20%, “the maximum allowed on a single day under stock-market rules, after it said losses in its U.S. office-loan portfolio will likely lead to a net loss for the year ending in March.” The annual loss will be the first in 15 years and its president will step down April 1. And then, Deutsche Bank “increased loss provisions in its U.S. commercial loan book nearly fivefold from 2022’s fourth quarter to 123 million euros, equivalent to $133 million.”

Concerns about conditions in CRE might push banks into restricting lending even more, which would reduce available financing and make the industry more dependent on alternative funding sources, like private equity, with significant higher financing costs than commercial banks.

Or as Morgan Stanley’s Mike Wilson put it to Bloomberg: “It’s not a systemic issue. It’s a weight on credit growth [and] the companies that are reliant on that kind of funding are going to see that’s a paperweight for them.”


Source:  GlobeSt.

money_hundred dollar bills with magnifying glass_shutterstock_2241523095 800x315

Commercial real estate got some indirect bad news.

The Securities and Exchange Commission sent letter exchanges to several community or regional banks about potential exposure to CRE loans, as the Wall Street Journal reported.

The agency contacted Alerus Financial and the holding companies behind Mid Penn Bank, Ohio Valley Bank and MainStreet Bank. The letters were “to request more clarity in their disclosures around the potential consequences from the failures of First Republic Bank, Silicon Valley Bank and Signature Bank.”

The three banks were closed and put into receivership by the Federal Deposit Insurance Corporation. Certain long-term bond assets that the banks held lost a lot of value as the Federal Reserve drove interest up in an attempt to curb inflation. When interest rates rise, bond values at previous lower interest rates lose value. These bonds were classified by the banks as held-to-maturity, meaning they could be treated as keeping their face value. But concerned depositors pulled large amounts of money out of the banks. That forced the institutions to sell bonds, which then were marked to market, losing liquidity and pushing the banks toward insolvency.

CRE loans aren’t the same as bonds, but there are two ways they could lose value. One is that increased interest rates could put borrowers with loans coming to maturity into a position where they can’t get refinancing. The lending bank would at least have to modify the loan, which could affect depositor trust and willingness to leave their deposits in place. Or the borrower could outright default.

The other way they could suddenly lose value is if the valuation of the property dropped — something happening broadly across all asset types, as GlobeSt.com has reported. That could leave the loan underwater, increasing risk and leaving depositors concerned and, again, possibly pulling out money and threatening the bank’s liquidity and potentially solvency.

Small, mid-size, and regional banks were the originators of many of the existing CRE loans. Unlike consumer mortgages, the banks don’t sell off the loans, leaving them holding all the risk.

“The SEC is worried that some of the banks may not be disclosing as much of their risk or exposure as they should to their investors,” Kenneth Chin, a partner at law firm Kramer Levin Naftalis & Frankel, told the Journal.

The SEC asked the banks to provide a more specific breakdown of CRE loan portfolios by property type, geography, and other factors.

Although the SEC has only made direct requests of these banks, the thousands of other institutions could see this as a pressure they too could face. Banks might further restrict their lending activity in 2024, increasing scrutiny and tightening underwriting standards, like loan-to-value ratios, even more than has previously happened.


Source:  GlobeSt.

hourglass_shutterstock_2102178886 800x315

There’s an interesting question about the current level of distress in commercial real estate. How much is there?

Some amount seems to be secret, as in not easily identified, instead being handled privately without an obvious full run-on distressed properties. And then there are properties on the brink but not yet in the distressed category.

MSCI’s US distress tracker report tries to make this clearer by discussing actual and potential distress. Distress “indicates direct knowledge of property-level distress,” they wrote.

“Known through announcements of bankruptcy, default and court administration as well as significant publicly reported issues — such as significant tenant distress or liquidation — that would exemplify property-level distress. This also includes CMBS loans transferred to a special servicer.”

Actual distress, according to the firm, totaled nearly $85.8 billion through the fourth quarter of 2023. Roughly $35.5 billion was office, $21.6 billion in retail, $14.7 billion in hotels, $9.6 billion in apartment, $1.6 in industrial, and $2.8 billion in other. But that is explicitly property-level distress.

Geographically that represents $10.3 billion for Mid-Atlantic, $13.4 billion in Midwest, $26.9 billion in Northeast, $8.6 billion in Southeast, $9.2 billion in Southwest, and $16.7 billion in West.

Loans privately modified to keep them from being written down or publicly disclosed would not be caught up in this category.

As the firm wrote, “Potential distress indicates that an asset’s current financial position has eroded and that it may become financial troubled. As of December, the value of assets classified as potentially troubled stood at $234.6b, or nearly three times that of distressed assets. Though apartments were responsible for the most significant slice of this value, new potential distress for multifamily assets seems to have moderated.”

That’s split up as follows: $67.3 billion in apartments, $54.7 billion in office, $35.5 billion in hotels, $34.9 billion in retail, $29.0 billion in industrial, and $13.3 billion in other.

Geographically, that represents $23.3 billion for Mid-Atlantic, $31.3 billion in Midwest, $47.5 billion in Northeast, $43.5 billion in Southeast, $33.3 billion in Southwest, and $55.5 billion in West.

“In the fourth quarter, the value of potential distress added to the market was lower for apartments than any other asset class,” MSCI wrote. “Of the $67.3b in multifamily potential distress, more than 30% of the value is tied to assets purchased in the last three years. Owners who made purchases at record-high prices may have found their assets landing on servicer watchlists as assumptions used to underwrite their acquisitions proved overoptimistic.”


Source:  GlobeSt.

upward trend written on white board_shutterstock_1745636096 800x315

You might know that Sound of Music sing-a-longs are a thing in live theater and online. You can bet that one of the favorites is Climb Every Mountain. If only triple net lease could step out of the spotlight.

Unfortunately, the sector seems to be providing encore performances as average closing cap rates keep their upward inclination, according to the Lomuto Report out of Northmarq.

“[The] indicators are saying we’re probably not done with rising cap rates just yet,” Chris Lomuto wrote. “Lots of existing inventory to burn off, maturing loans that may be difficult to roll over, developers needing to recycle capital, tight spreads, and a dearth of 1031 buyers. These are not traditionally a recipe for stable or falling cap rates.”

The mechanisms at work seem clear. In short, there’s more supply and less demand, squeezing out the value owners can claim and lowering the willingness of buyers to pay higher prices. As long as the conditions continue, there’s upward pressure on closing cap rates.

Though Lomuto notes some trends that could eventually head things off and restore a more dynamic market. For example, the average asking cap rate trend for all NNN started to rise in May 2022, when they were about 5.25%. With some minor ups and downs, it’s continued to rise and has gained roughly 100 basis points to 6.25%. Owners are recognizing that they can no longer expect as much as they could have in the near past when markets were at a high and the full impact of higher interest rates hadn’t yet been felt.

With the rise in asking cap rates had been compression of the gap between them and benchmark yields from, in the case of the federal funds rate, 587 basis points in January 2021 to 91 basis points in December 2023. The gap to the 10-year Treasury had been 488 basis points in that same January and now are 222. The S&P 500 earnings were spaced out by 295 and now that gap is 239. All in all, the biggest gap is within under 240 basis points.

Where things can get a little odd is looking at cap rates by product type. Lomuto shows a number of categories: auto and car wash, convenience and gas, dollar stores, grocery, industrial, office, pharmacy, and QSR. Measured from peak pricing, pharmacy is up by only 75 basis points (he points out that issues with Rite Aid and Walgreens should have had more effect). Grocery, one of the die-hard categories, has seen cap rates up over dollar stores. And office seems up only by 50 basis points — okay, more than odd, more like crazy.

When transactions are thinner than usual, “it’s very important to look critically at individual comps, including a thoughtful survey of what else is on the market now, when quoting a cap rate.”


Source:  GlobeSt.

10-year-treasury-yields 800x315

Bond traders are getting certain that a long-time aberration in how Treasury bond prices and yields work is about to head back to normal.

They expect that the yield on the 10-year Treasury will rise above the 2-year (though academics often monitor the 3-month and the 10-year), Bloomberg reports.

A look at the numbers at the Federal Reserve Bank of St. Louis’ FRED website shows that July 5, 2022, was when the yields on the 2-year and 10-year Treasurys were the same. Since then, the 10-year sunk below, and there’s been an inverted yield curve. The 3-month and 10-year difference inverted on October 25, 2022. A long haul, either way you look at it.

Inversions lasting for an extended period are generally taken to mean that there’s a recession on its way … eventually. As US News & World Report noted last year, the average time between an inversion and a recession is 12 to 24 months, although the shortest period in 2019 was six months.

The theory behind the yield tea leaves is that investors are sure there’s a recession coming and so they lock in even at lower rates now because they’re sure the Federal Reserve will cut rates to stimulate the economy, making Treasury yields drop.

Harley Bassman, a big name in bonds, told Bloomberg earlier in the month, “It’s done. Stick a fork in it, man. The 10s aren’t moving.” Instead, he expects yields on the short end of the curve to drop and normalize the yield curve.

Kathryn Kaminski, chief research strategist at AlphaSimplex Group, told Bloomberg, “The question we are asking – given the wide range of outcomes – is what is that steeper yield curve? Is that going to be cuts on the short end or could it possibly be, unexpectedly, that we see weakness in long-term bonds and we have a longer time to wait for cuts – and we actually see a steepening from the long end.”

Bill Gross, another bond expert, said on social media that the Treasury 10-year with a 4% yield, around which it has lately hovered, is “overvalued.” Jeffrey Gundlach, founder, CEO, and chief investment officer of Doubleline, a money management firm that is a big player in the bond market. He said in a December 2023 CNBC interview that when the yield level of the 10-year Treasury market goes below 4%, it sounds “almost like a fire alarm” and that the 10-year yield would drop to the low 3s by sometime this year.

“In normal times it’s the short rate that comes down sharply given a recession is coming, and that causes the dis-inverting,” said Tobias Adrian, director of the International Monetary Fund’s monetary and capital markets department, told Bloomberg. “But now the US is likely to have a soft landing and so basically the curve could just flatten.”

But then, the 10-year yield has been climbing a bit over the last week, the 3-month has been steady, and the 2-year has been increasing. Some of the prognosticators will be right, others will be wrong, unless things manage to stay in a rough limbo, leaving everyone wondering. But there’s no definite answer right now.


Source:  GlobeSt.